
- Output, new orders and purchasing all rise at fastest rate in over four-and-a-half years
- Output price inflation at three-month high
- Rate of job creation remains modest
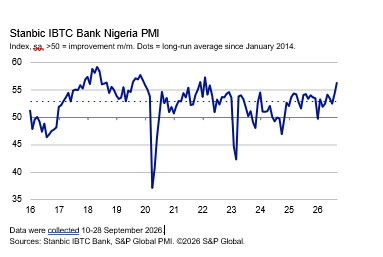
September data signalled strengthening growth momentum in Nigeria’s private sector as a rapid rise in new orders spurred the fastest increase in business activity since February 2022. With workloads rising, companies ramped up purchasing activity and took on extra staff, although employment rose only modestly.
Meanwhile, inflationary pressures were also marked, with companies increasing their selling prices at the fastest pace in three months in response to higher input costs.
The headline figure derived from the survey is the Purchasing Managers’ Index™ (PMI®). Readings above 50.0 signal an improvement in business conditions on the previous month, while readings below 50.0 show a deterioration.
The headline PMI increased for the second month running in September to 56.4, from 54.3 in August. The latest reading signalled a marked improvement in the health of the private sector, and one that was the most pronounced in just over four-and-a-half years.
A key factor behind the improvement in overall business conditions was firms’ success in securing new orders in September. Improving customer demand and the launch of new products helped lead to an eighth consecutive monthly rise in new business, and one that was the strongest since February 2022. In turn, business activity also increased at the sharpest pace since that month.
The latest rise in output was widespread across the different parts of the economy covered by the survey. Indeed, sector data pointed to marked expansions across all four monitored categories.
Efforts to keep on top of workloads amid sharply rising new orders led companies to expand their purchasing activity markedly in September. In some cases, inputs had been bought in anticipation of further demand improvements in the months ahead. Higher input buying fed through to a marked accumulation of inventories, the greatest since the end of 2021. Prompt payments to suppliers reportedly ensured that items were delivered in a timely manner, and vendor performance improved for the third month running as a result.
Companies also hired additional staff in September, but the rate of job creation was only modest. Moreover, where new workers were hired, this was often only on a temporary basis to help complete specific projects. Nonetheless, the expansion in capacity during the month helped firms to keep on top of workloads despite the rapid rise in new orders. Backlogs of work decreased for the second month running, albeit only marginally.
A further sharp rise in purchase prices was recorded at the end of the third quarter, with the rate of inflation at a three-month high. According to respondents, higher fuel costs were often behind the latest increase, while there were also reports of rising prices for animal feed, foodstuffs and other raw materials.
The rate of staff cost inflation also quickened as companies helped their workers deal with higher living costs and offered incentives for completing projects on time.
Firms subsequently passed higher input prices through to customers and selling prices increased rapidly as a result. In line with the trends in purchase prices and staff costs, the latest rise in output prices was the fastest since June.
Companies were more optimistic regarding the 12-month outlook for business activity in September. Positive sentiment often reflected business expansion plans, including the opening of new branches and intentions to begin exporting products. The securing of new customers and stockbuilding were also factors set to support output over the coming year, according to panellists.
Comment
Muyiwa Oni, Head of Equity Research West Africa at Stanbic IBTC Bank commented:
“Overall business conditions improved significantly in September, with the headline PMI (56.4 points vs August: 54.3 points) rising to a level not seen since February 2022 (57.3 points), thereby ensuring a better third quarter for business activities relative to the second quarter of the year. Indeed, all the four sectors monitored by the survey recorded significant improvement in September, as firms noted improving customer demands as ensuring they secure new orders during the period while also introducing new products into the market. Based on this, companies also increased pace of hiring although bulk of these workers were hired on a temporary basis to complete specific tasks.
Elsewhere, higher fuel prices continue to feed into increase in transport costs. This, in addition to increase in raw material prices, rising staff costs, as well as the prices of other food products helped to ensure that input costs maintained their uptrend. This then fed into output prices increasing to a three-month high in September.
The strong end to the quarter implies that the PMI prints in Q3:26 are consistent with a likely 4.56% y/y GDP growth in Q3:26, taking the full year 2026 growth estimate to approximately 4.4% y/y from 3.87% y/y recorded in 2025. The non-oil sector is expected to perform better in 2026 compared to 2025 as more sectors contribute to improvement in GDP growth rate this year. Among the three broad sectors of the economy, we expect the manufacturing sector to see the biggest boost to its growth amid the low statistical base effects from 2025 while ICT, trade, real estate, and finance & insurance will likely remain the biggest drivers of the services sector’s growth.”